







Mr. Goodwin is everything you want in an attorney: professional, honest, thorough, and genuinely caring. He always explains things clearly, so I understood exactly what was happening and what to expect next. His attention to detail and persistence really stood out. Looking back, I feel lucky to have found him. He guided me through the whole process expertly, and I deeply appreciate all his hard work. Would definitely recommend him to anyone needing legal help.
Call Today:
212-233-1233
What is a contingent beneficiary of an estate or an account
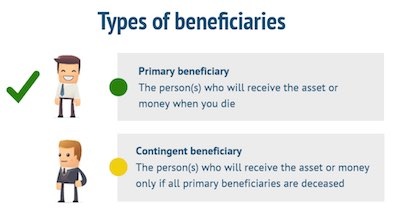
A contingent beneficiary is a person or entity nominated to receive an asset on someone’s death if the primary beneficiary cannot inherit it, for example because the primary beneficiary died first, refuses to accept the asset, or cannot be located. Contingent beneficiaries are normally designated on assets that carry beneficiary designations, such as life insurance policies, IRAs, annuities and 401(k)s, and they are also named in wills. A contingent beneficiary can only exist together with a primary beneficiary.
An Example: Life Insurance
John is married to Linda, and they have two children, Tom and Mike. John’s life insurance policy names Linda as the beneficiary. Lawyers always recommend naming a contingent beneficiary as well, so that if the primary beneficiary cannot receive the asset for any reason, it goes to a person the insured chose. John can designate Tom and Mike as contingent beneficiaries in equal shares, so that if Linda predeceases John, or for some other reason refuses or fails to receive the insurance proceeds, the proceeds go to Tom and Mike 50%-50%. If John names no contingent beneficiary and Linda predeceases him, the insurance proceeds are paid to John’s estate.
An Example: A Will
In the same family, John writes a will leaving his residuary estate to Linda. The provision would read something like: “I give, devise, and bequeath to my spouse, Linda, all the rest, residue and remainder of my estate, whether real, personal or mixed of whatsoever kind.” To name a contingent beneficiary, John adds: “If my spouse, Linda, does not survive me, I give, devise and bequeath all the rest, residue, and remainder of my estate to my children, Tom and Mike, in equal portions each.” Tom and Mike are then contingent beneficiaries who inherit the residuary estate if Linda predeceases John.
If John named no contingent beneficiary and Linda predeceased him, the residuary estate would be distributed under New York’s laws of intestacy, because the will would no longer name a qualified beneficiary for it. For this reason we recommend naming several contingent beneficiaries in a specified order, so that someone the person actually chose is always available to receive the asset.
Contingent Beneficiary vs. Contingent Remainder Interest
Some people confuse a contingent remainder interest with a contingent beneficiary. A contingent remainder interest is a future interest that depends on the happening of an event. If John’s will says, “I give, devise, and bequeath $100,000 to Tom if Tom is married,” Tom has a contingent remainder interest of $100,000 in John’s estate. If Tom is not married when John dies, Tom is not entitled to the $100,000, and the amount falls back into John’s residuary estate.
The difference is that a contingent beneficiary inherits completely and without condition when the primary beneficiary cannot, while the holder of a contingent remainder interest inherits only if the stated condition occurs. Contingent remainder interests can be used in wills, but they are more commonly used in trusts.
Multiple Levels of Contingent Beneficiaries
Effective estate planning typically designates several layers of beneficiaries: the primary beneficiary, who is first in line; a first-level contingent beneficiary, who takes if the primary cannot; a second-level contingent beneficiary, who takes if both the primary and the first contingent cannot; and further levels to cover remote scenarios. Each layer protects against the case where several beneficiaries cannot take. Without backups, the asset falls into the default rules, payment to the estate or intestacy, which the owner may never have wanted.
Common Triggering Events
| Event | How it arises |
|---|---|
| Primary beneficiary dies before the owner | The most common scenario, especially when the primary beneficiary is a spouse of similar age. |
| Primary beneficiary dies at the same time as the owner | A plane crash, car accident or other common disaster. |
| Primary beneficiary refuses the asset | A disclaimer can be used for tax planning or to redirect assets to other beneficiaries. |
| Primary beneficiary cannot be located | Estranged relatives or beneficiaries with whom contact has been lost. |
| Primary beneficiary is disqualified | Divorce of a spouse-beneficiary, conviction of a crime against the owner, or another disqualifying event. |
The 120-Hour Rule
EPTL § 2-1.6 contains New York’s 120-hour rule: a beneficiary who fails to survive the testator or asset owner by 120 hours is treated as having predeceased. The rule prevents assets from passing through two estates in quick succession, avoids unnecessary double estate tax inclusion, and provides certainty when the order of death is unclear. It can be overridden by a will or beneficiary designation that requires a different survival period. Many estate plans specify a longer period, such as 30, 60 or 90 days, so that the contingent beneficiary receives the asset directly rather than through the primary beneficiary’s estate.
Naming Trusts as Contingent Beneficiaries
A trust can serve as a primary or contingent beneficiary. A children’s trust receives the assets if both parents die, so that minor children do not take outright. A special needs trust protects assets for a disabled beneficiary without disqualifying them from government benefits. A spendthrift trust protects assets from a beneficiary who would mismanage them, and a generation-skipping trust holds assets across multiple generations for tax efficiency. Designating a trust as beneficiary requires specific drafting so that the trust can receive the assets properly, and retirement account designations to trusts follow specific rules under the SECURE Act that require careful attention.
Per Stirpes vs. Per Capita
When several related contingent beneficiaries are named, such as children, the distribution method matters. Under per stirpes (by representation), if a beneficiary dies before the owner, that beneficiary’s share passes to their own children; each branch of the family tree keeps its proportional share. Under per capita, only the surviving beneficiaries take, and a deceased beneficiary’s share is divided among the survivors.
For example, an owner has three children, A, B and C. B dies before the owner, leaving two children. Per stirpes, A and C each receive one-third and B’s two children split B’s third, one-sixth each. Per capita, A and C each receive one-half and B’s children receive nothing. The method should be stated in the beneficiary designation, because the default rules vary by asset type and may not match the owner’s wishes.
Contingent Beneficiaries for Different Asset Types
| Asset | Contingent beneficiary considerations |
|---|---|
| Retirement accounts (401(k), IRA, 403(b)) | The SECURE Act limits distributions to non-spouse beneficiaries. Contingent designations are typically allowed and follow the same rules as primary designations. |
| Life insurance | Most policies allow multiple primary and contingent beneficiaries with specified percentages. Changes typically require a form submitted to the insurer. |
| Bank and brokerage accounts | POD and TOD designations may or may not support contingent beneficiaries, depending on the institution’s forms. |
| Annuities | The rules depend on the annuity type and whether it is in the accumulation or payout stage. |
| Real estate (in states allowing TOD deeds) | TOD deeds generally do not support contingent beneficiaries, which is one reason living trusts are preferred for real estate. |
| Pour-over will with a trust | The contingent beneficiary structure is built into the trust rather than the will. |
Updating Contingent Beneficiary Designations
Designations should be reviewed when a beneficiary dies or has a major life change, when new family members arrive through birth, adoption or marriage, when relationships change through divorce or estrangement, when the owner’s wishes change, and in any event every three to five years. Outdated designations produce surprising and unwanted results; a review takes little time and prevents significant problems.
Disclaimer as a Planning Tool
A beneficiary can disclaim (refuse) an inheritance, which then passes to the contingent beneficiary. Disclaimers are used for estate tax planning when the primary beneficiary does not need the assets, to redirect assets to beneficiaries who need them more, to skip a generation for tax efficiency, to keep the assets away from the primary beneficiary’s creditors, and to resolve family conflicts about distribution. To be effective, a disclaimer must be made within nine months of death, in writing, signed and acknowledged, and not accompanied by acceptance of any benefits. The disclaimed assets pass as if the disclaimant had predeceased.
If you would like help naming or reviewing contingent beneficiaries, or if a beneficiary designation is being disputed, the Law Offices of Albert Goodwin can help. Call us at 212-233-1233 or email [email protected].

About the Author
Albert Goodwin Esq. is a licensed New York attorney with over 18 years of courtroom experience. His extensive knowledge and experience make him well-qualified to write authoritative articles on a wide range of legal topics. He can be reached at 212-233-1233 or [email protected].



